Related Topics:
Electricity Adapters Converters Europe-
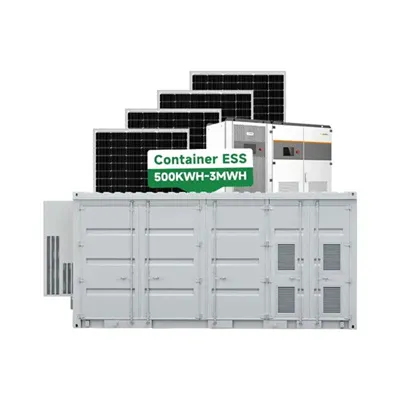
Solar power generation system in Southern Europe
According to the latest analysis by AleaSoft Energy Forecasting, Italy, Portugal and Spain set new daily solar power generation records at the end of June 2025, marking a breakthrough in the application of photovoltaics in Southern Europe.
FAQs about Solar power generation system in Southern Europe
Will solar power grow in Europe in 2023?
SolarPower Europe's new European Market Outlook for Solar Power 2023-2027 reveals a record 56 GW of solar installations in Europe in 2023. This marks the third year of annual growth rates of at least 40%. The annual report predicts slower growth in 2024, with the annual market set to increase by only 11% - delivering 62 GW.
What is the future of solar energy in Europe?
Solar PV and wind energy become the cornerstone of the transformed energy system, with solar PV being crucial for achieving self-sufficiency. By 2050, 5.1 TW of solar and 1.3 TW of onshore and offshore wind capacity will be installed across Europe (see Supplementary Fig. 13), taking up 57% and 36% of the electricity generation, respectively.
Is solar the fastest growing energy source in Europe?
IRENA: Solar the fastest growing energy source worldwide This March, solar came to the rescue of Europe's high power prices thanks to sunnier days and increased capacity, with 65 GW added in 2024 alone. As a result, the share of renewables in the power mix was 15% higher in March compared to February, but still 1% lower than in March 2024.
Which EU countries install the most solar in a year?
Germany also now hold's the record for the most solar installed by an EU country in one year, taking over Italy's 12-year record of 9.3 GW in 2012. Spain (8.2 GW), Italy (4.8 GW), Poland (4.6 GW), and the Netherlands (4.1 GW) follow Germany and round out the top five EU solar markets.
How much does solar power cost in Europe?
According to Eurelectric, solar now accounts for over 10% of the continent's electricity mix. This solar boost, combined with improved nuclear generation and milder weather, decreased power prices to €90 per megawatt hour (MWh) compared to the highs of €126/MWh seen in February and €112/MWh in January.
How many European homes are powered by solar in 2023?
BRUSSELS, Belgium (Tuesday 12th December 2023): Almost 17 million more European homes were powered by solar in 2023, due to a 40% growth in solar installations from 2022. Compared to the 40 GW of solar installed in 2022, 2023 brought 55.9 GW of new solar capacity across the EU27. New solar in Europe in 2023. A booming rooftop segment.
-
Southern Europe Energy Storage Power Wholesale
By leveraging Wood Mackenzie's Europe Power Service price data (covering wholesale power, ancillary services and capacity markets), the report evaluates current investment opportunities in battery storage projects across the region, with a particular focus on Germany, Spain and France.
FAQs about Southern Europe Energy Storage Power Wholesale
Which country is promoting the development of residential energy storage?
In terms of residential energy storage, the Polish government has launched Moj PRD 5.0 subsidy program to encourage the development of residential energy storage. Sweden's installed battery storage capacity is expected to grow from 503 MW in 2023 to 3.8 GW in 2030, with high revenue levels in the ancillary services market driving the market growth.
Why should you invest in battery storage in Europe?
In Europe, the capacity of renewable energy sources is growing very rapidly, while traditional power plants are slowly being decommissioned. That's creating a unique new opportunity for investors amid the emerging demand for battery storage, which provides balance to electricity markets.
Is energy storage a good investment in Europe?
Compared to classic renewables, energy storage has really only become an investable asset in Europe over the last few years on the back of technology advances, market price signals, and government support mechanisms.
How do energy storage assets make money in Europe?
For short-duration energy storage assets, there are really three key revenue streams for energy storage assets in Europe. The first one is capacity payments, which have become a broadly implemented policy measure by governments to support system reliability and incentivize the installation of certain new power asset types.
What is the future of energy storage in Ireland?
Future market potential is concentrated in pre-sheet energy storage and energy storage co-located projects, residential and commercial storage market space is not large. Ireland's battery storage capacity is expected to grow from 792 MW in 2023 to 3.9 GW in 2030, mainly in the pre-table storage market.
How many energy storage assets are there in the UK?
Trading strategies are becoming increasingly sophisticated with a strong reliance on technology and big data analytics. In the UK — the most advanced battery market in Europe — there are currently 23 entities trading energy storage assets.
-
Western Europe Iron-based Liquid Flow Battery
Dutch energy storage company Elestor is addressing this challenge with its hydrogen-iron flow battery: a scalable, safe, and geopolitically independent solution purpose-built for large-scale, long-duration energy storage.
FAQs about Western Europe Iron-based Liquid Flow Battery
What is Iron-Flow batteries?
This unique feature allows for cost-effective scaling, essential for large-scale applications. Developed using an advanced metal complex and membrane, Iron-Flow Batteries is based at the Paris Flow Tech platform – a premier hub for innovation in continuous flow chemistry.
Are aqueous iron-based flow batteries suitable for large-scale energy storage applications?
Thus, the cost-effective aqueous iron-based flow batteries hold the greatest potential for large-scale energy storage application.
Are iron-based aqueous redox flow batteries the future of energy storage?
The rapid advancement of flow batteries offers a promising pathway to addressing global energy and environmental challenges. Among them, iron-based aqueous redox flow batteries (ARFBs) are a compelling choice for future energy storage systems due to their excellent safety, cost-effectiveness and scalability.
Are all-liquid flow batteries suitable for long-term energy storage?
Among the numerous all-liquid flow batteries, all-liquid iron-based flow batteries with iron complexes redox couples serving as active material are appropriate for long duration energy storage because of the low cost of the iron electrolyte and the flexible design of power and capacity.
Why is electrolyte engineering important for all-iron flow batteries?
For all-iron flow batteries, electrolyte engineering is particularly important to mitigate HER, which competes with iron redox reactions. Additionally, optimizing carbon-based electrodes through surface modifications or catalyst coatings can enhance charge transfer efficiency.
Are all-iron flow batteries a promising prospect for LDEs?
Combined with high reliability, high performance and low cost, the all-iron flow battery demonstrated a very promising prospect for LDES. The authors declare that they have no known competing financial interests or personal relationships that could have appeared to influence the work reported in this paper.
-
What is the energy storage battery industry in Western Europe
The market for battery energy storage systems (BESS) in Europe is expected to grow on the back of a list of elements including growth in the uptake of renewable energy, favorable government policies, upgrading of grid infrastructure, rising demand for electricity, falling battery costs, improved energy security, and higher utilization of smart grids and electric vehicles.
FAQs about What is the energy storage battery industry in Western Europe
How can European policymakers help the battery storage sector?
ecomendationsHow can European policymakers help the battery storage sectorBattery storage systems are essential for strengthening the EU's energy security and competitiveness by enhancing flexibility, providing ancillary services to secure the grid, maximising the use of renewable energy, and effectively dealing with energy pr
How to generate revenue from battery energy storage systems in Europe?
To generate revenue from battery energy storage systems in Europe, companies need to be strategic and take advantage of different markets and services. Capacity markets, for example, offer a stable source of income: payment is made for the provision of reserve capacity.
What percentage of European battery energy storage systems are lithium ion?
By battery type, lithium-ion commanded 92% of the European battery energy storage system market share in 2024; flow batteries are projected to expand at a 16.66% CAGR through 2030.
When was battery storage installed in Europe?
of battery storage capacity was installed in Europe at the end of 2023. Your expert for questions The European energy landscape is undergoing a profound change: the driver of this development is the ever-faster integration of renewable energy sources in order to reduce carbon emissions and achieve climate targets.
Why is battery production important for the EU?
Batteries, widely used in the transport and energy sectors, are central to the global energy system. They will be key to the EU's clean energy transition, industrial future and strategic autonomy. Boosting the industrial base for battery production is therefore a key task for the EU.
Which countries are leading the battery storage market in 2024?
continue to lead the market and deliver almost 70% of the annual capacityIn 2024, Europe's top three battery storage markets – Germany, Italy, UK – solidified their dominance, with Austria and Sweden closing the 'top 5' ranking (see Fig. 2). 2024 marked the first year when reac
-
Industrial Energy Storage in Southern Europe
It offers near real-time data on the deployment of storage facilities across Europe, including an interactive dashboard and map, and identifies all the technologies, from battery storage to pumped hydro, and emerging technologies like hydrogen storage and thermal storage.
FAQs about Industrial Energy Storage in Southern Europe
What is the European energy storage inventory?
A new interactive platform delivers real-time clean energy storage insights as Europe shifts toward sustainable energy sources. Energy storage helps to balance supply and demand. The European Energy Storage Inventory is the first of its kind at European level to show all forms of clean energy storage solutions.
Which country is promoting the development of residential energy storage?
In terms of residential energy storage, the Polish government has launched Moj PRD 5.0 subsidy program to encourage the development of residential energy storage. Sweden's installed battery storage capacity is expected to grow from 503 MW in 2023 to 3.8 GW in 2030, with high revenue levels in the ancillary services market driving the market growth.
Which energy storage technology is the most popular in Europe?
Pumped hydro is the most widely used technology for energy storage in Europe and worldwide, but batteries and hydrogen have come into the spotlight over the last decade as a recent trend in the energy storage market.
What is the future of energy storage in Ireland?
Future market potential is concentrated in pre-sheet energy storage and energy storage co-located projects, residential and commercial storage market space is not large. Ireland's battery storage capacity is expected to grow from 792 MW in 2023 to 3.9 GW in 2030, mainly in the pre-table storage market.
Which country has the largest hydro storage capacity in Europe?
Because of water resources availability and tailored energy policies, Germany, Italy, and Spain accounted for the largest pumped hydro storage capacity in the region, ranging between over nine gigawatts in Germany and 5.6 gigawatts in Spain in 2023. Discover all statistics and data on Energy storage in Europe now on statista.com!
What is Italy's energy storage capacity in 2023?
Italy's installed energy storage capacity in 2023 is 3.9 GW, and is expected to increase to 18 GW by 2030, mainly in the pre-table energy storage and household storage markets.
-
Western Europe Power Supply Solar System Production
This ambition faces a potential supply resilience risk: Europe currently relies almost entirely on imports from one country for the solar PV panels it needs. China dominates the solar-PV supply chain with almost 95 percent of the world's wafer production (Exhibit 2). It is home to the top. Our analysis suggests that the costs of solar-PV manufacturing in Europe at scale for the full value chain will be at a 20 to 25 percent disadvantage against current lowest cost levels—if. For European-based companies to succeed in building feasible, long-term competitive positions in the global solar-PV supply chain and enable a viable European industry, the success formula will likely combine highly ambitious and cost-competitive.
FAQs about Western Europe Power Supply Solar System Production
Does Europe have a solar supply chain?
SolarPower Europe has released a report mapping Europe's solar PV module production equipment capacity, identifying at least 38 companies involved in manufacturing key machinery for the solar supply chain, including cells, ingots, wafers, and polysilicon.
Does Europe need a solar PV system?
Europe relies on solar photovoltaic (PV) as one of the main energy sources in its climate roadmap. Europe has been a pioneer and leader in PV production, and the installation targets are continually increasing via Renewable Energy Directive revisions.
Will the EU solar PV market grow in 2025?
The new mid-year solar PV EU market analysis from SolarPower Europe reveals that for 2025, the annual market is expected to contract for the first time since 2015, with a projected -1.4% growth in the most likely scenario. This follows the exceptional annual market expansions in 2022 (+ 47%) and 2023 (+51%), and flattened growth in 2024 (+3.3%).
Will Europe be able to host 723 GW of solar PV by 2030?
The current trend suggests that Europe will fall short of its goals, hosting 723 GW of solar PV by 2030, compared to the required 750 GW. The analysis comes as solar's performance for Europe hits the headlines. According to Ember, for the first time, solar delivered most of the EU's monthly electricity in June.
Does Europe still produce PV panels?
Europe's share in the global production market of PV panels fell from over 30% in 2010 to less than 5% today. The European region still has several production sites located in industrial clusters, offering logistical advantages and proximity to customers.
Will Europe become a major solar-PV market?
Germany alone aims to install 215 GW by 2030, adding 160 GW of new capacity on top of the current 58 GW, almost scaling the market by a factor of four. 2 With these ambitions in place, Europe would maintain its position as one of the major solar-PV markets in the world, alongside China, India, and the United States.
-
Eastern Europe New Energy Photovoltaic Solar Panels
Large-scale deployment of innovative bifacial photovoltaic (PV) systems, oriented east and west instead of the conventional south-facing setup, could significantly help fix energy price swings, cut fossil fuel use, and strengthen Europe's clean energy path, new research finds.
FAQs about Eastern Europe New Energy Photovoltaic Solar Panels
Is Eastern Europe a promising market for solar energy deployment?
Eastern Europe indeed represents a promising market with untapped potential in solar energy deployment, given its early-stage market development. Solar energy, being highly competitive and increasingly cost-effective, is expected to play a key role in the region's energy future.
Which European countries have the most solar energy?
The age of solar energy is dawning in Eastern Europe: According to the European industry association SolarPower Europe, Poland has been one of the top ten leading countries in Europe in terms of PV deployment since 2016. Hungary has joined the list after adding 1.6 gigawatts (GW) of PV capacity in 2023, a 45 percent increase over the previous year.
Why is Eastern Europe getting more solar power?
The country's total solar power output increased dramatically, by 970 megawatts (MW) to be exact. The PV boom in Eastern Europe is driven by a desire for greater energy independence and a commitment to environmental and climate targets. Other key drivers are cost efficiency, technological advances and subsidy policies.
Does RWE have a solar portfolio in Poland?
RWE began construction on a new solar portfolio in Poland last month. Image: RWE Eastern Europe has seen exponential growth in its solar sector in recent years, with three of the five countries which exceeded 1GW of installed solar capacity in Europe in 2023 – Bulgaria, the Czech Republic and Romania – all in the east.
Is Eastern Europe a good place to invest in solar?
Eastern Europe is set to be pivotal in the solar industry, given its cost advantages and growth potential. Solar's affordability and accessibility make it ideal for achieving the region's decarbonisation targets. Already, we see substantial project development across the Baltics, Balkans, Bulgaria, Romania and other areas.
Where does solar power come from in Europe?
Eastern Europe is often overlooked in discussions about solar power generation in Europe, where the likes of Germany and Spain dominate the growth in deployed solar electricity production.